
Dental Practice Earnouts Explained: How to Protect Your Future Payment
An earnout offer can be deceiving: the headline value may look attractive, but part of the payout still depends on how the practice performs after the sale. The buyer may agree to pay a higher total price, but part of that value only arrives if the practice hits specific targets after closing. If those targets are missed, the seller may never receive the full amount shown in the offer.
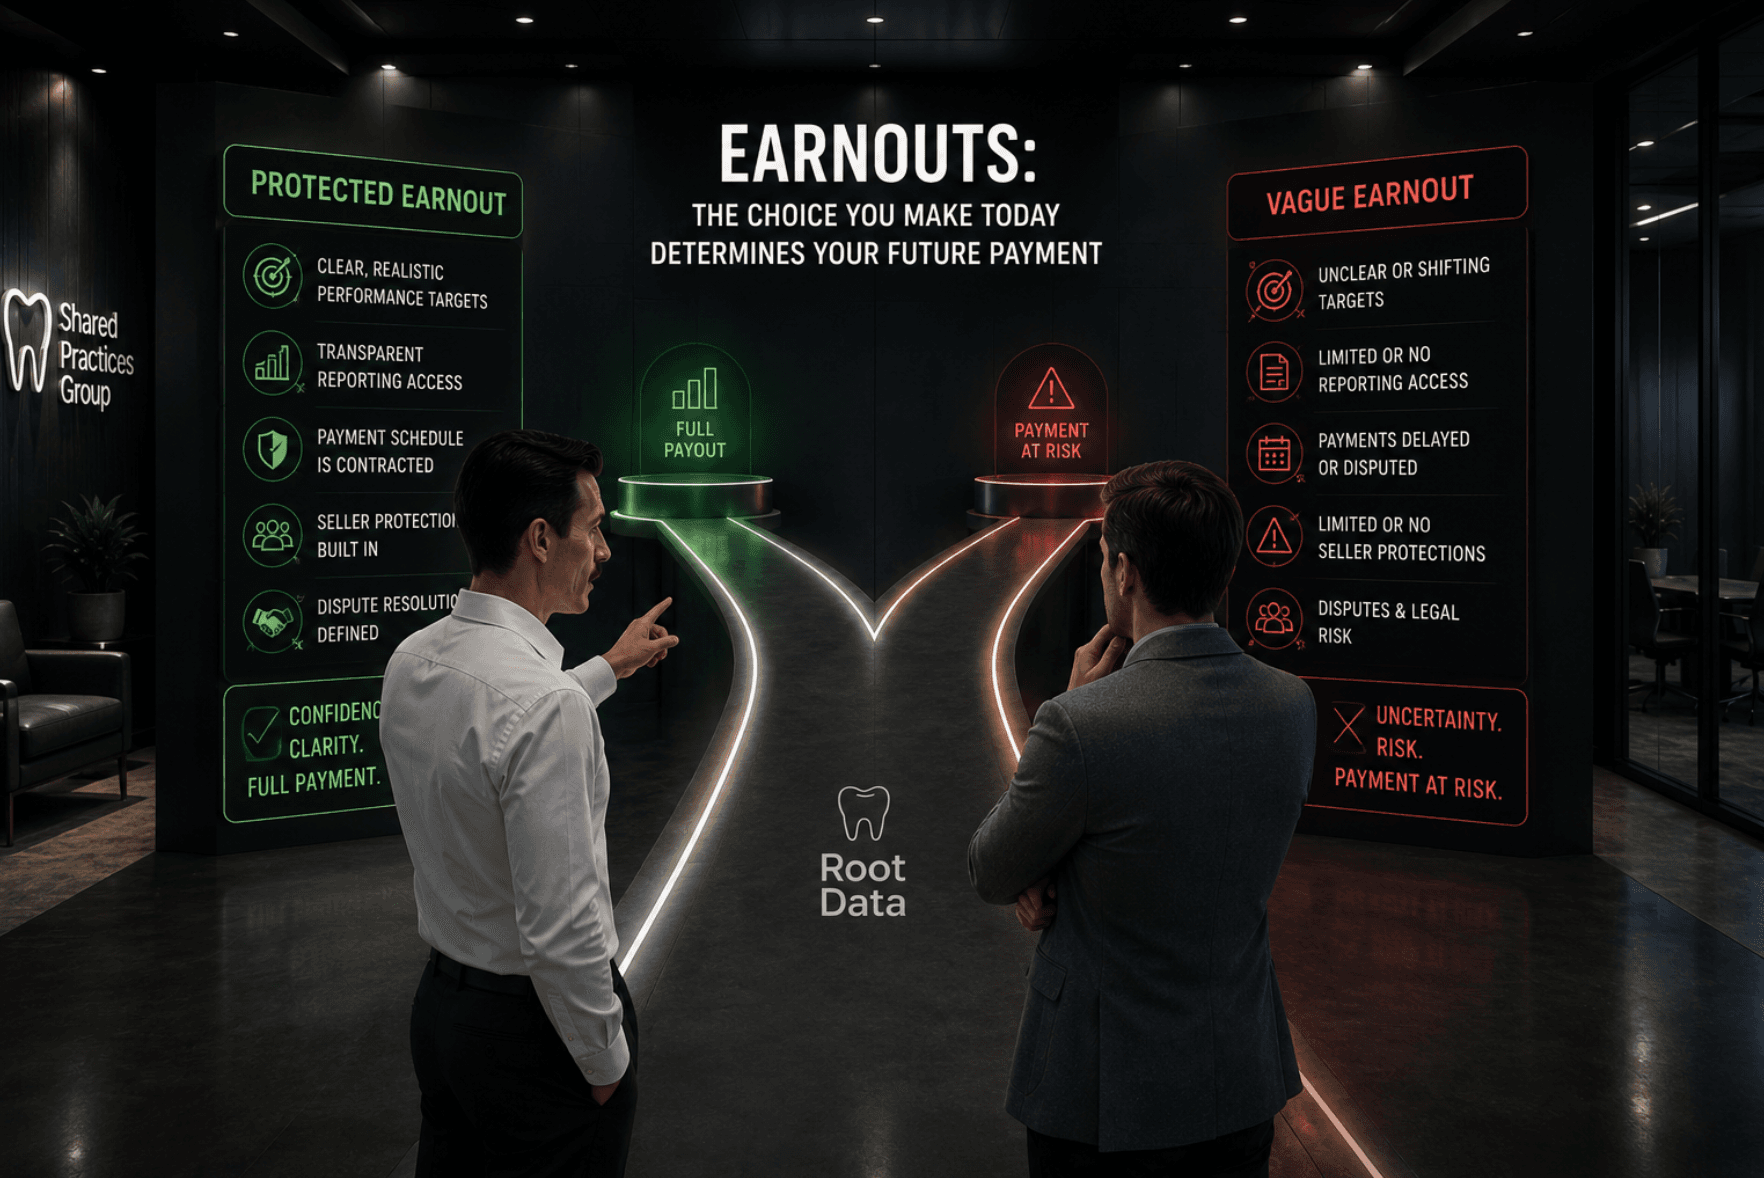
An earnout can make a dental practice offer look more attractive than the cash available at closing.
The buyer may offer a higher total purchase price, but part of that amount depends on the practice meeting specific targets after the sale. If those targets are missed, the seller may never receive the full headline value.
For anyone considering selling a dental practice, that distinction matters.
Earnouts can help bridge a valuation gap and reward strong post-sale performance. But the contingent portion should be evaluated separately from the amount payable at closing.
Before accepting an earnout, understand how the payment is calculated, who controls the factors affecting it, and what could prevent you from receiving it.
What Is a Dental Practice Earnout?
An earnout is a future payment tied to agreed conditions, often involving post-sale business performance.
Instead of paying the entire potential purchase price at closing, the buyer agrees to make an additional payment if those conditions are met.
The agreement might use production, collections, earnings, patient retention, or another defined measure. Some arrangements also connect eligibility to the seller’s continued employment.
For example, a buyer might offer $2 million at closing and another $400,000 if collections remain above a specified level during the following two years.
The potential value is $2.4 million. The additional $400,000 remains contingent on the agreement’s terms.
An earnout is also different from a fixed deferred payment or an escrow held for indemnification claims. Each has its own conditions and risks, so the offer should identify them separately.
Why Buyers Use Earnouts
Buyers use earnouts to share uncertainty about future performance.
A practice may look strong before closing, but the buyer still needs to consider whether patients and staff will stay, whether clinical production will continue, and how the ownership transition will affect earnings.
An earnout places some of that performance risk on the seller.
It can also help resolve a disagreement over value. If the seller expects growth and the buyer is less certain, an additional payment tied to results may let both sides move forward.
The challenge is that the seller may no longer control the business after closing.
That makes the metric, operating arrangements, and payment conditions as important as the potential amount.
Focus on the Metric Behind the Payment
A collections target differs from a production target. An earnings target introduces different questions again.
Production reflects the value of care recorded as delivered. Collections reflect payments received. Neither alone establishes profitability.
A collections-based earnout may be affected by billing processes, insurance payment timing, refunds, patient payment arrangements, and the treatment of existing accounts receivable.
An EBITDA-based earnout may be affected by staffing costs, provider compensation, management charges, and other expenses included in the contractual calculation.
The agreement needs to explain how the chosen measure works.
Which revenue and expenses count? How are adjustments handled? Which reporting period applies? What happens if accounting practices change?
Understanding the underlying dental metrics helps sellers ask better questions. The contract then needs to translate those concepts into a precise formula.
Test the Target Against Actual Practice Performance
Evaluate a target against the practice’s history and the operating conditions expected after closing.
Review production, collections, provider schedules, patient activity, hygiene performance, and relevant expenses over comparable periods.
Look beyond the average. Seasonality, staffing gaps, provider absences, and unusual collections can affect whether a threshold is realistic.
Then examine what will change.
If the selling dentist plans to reduce clinical days, a target based on the previous schedule may require replacement capacity. If the buyer plans to change insurance participation, staffing, fees, or office hours, historical results may not provide a reliable forecast on their own.
Dental analytics software can help organize the operational evidence behind those discussions.
It can show whether an assumption aligns with past performance and flag questions that need further analysis. It cannot guarantee that a target will be achieved.
Who Controls the Outcome After Closing?
This is one of the most important questions in any earnout.
The buyer may control staffing, scheduling, marketing, insurance participation, fees, recruitment, equipment investment, and office hours.
Those decisions can affect the seller’s ability to meet the target.
For example, a practice may have enough patient demand to maintain production but lack the provider coverage needed to deliver care. A collections target may become harder to reach if billing follow-up deteriorates.
The seller should understand which responsibilities remain under their control and which move to the buyer.
Discuss with transaction counsel whether the agreement should address operating commitments, changes that affect the calculation, and protections against conduct that undermines the earnout.
General assurances are less useful than clear terms describing how foreseeable situations will be handled.
Dental Practice Management Still Matters During the Earnout
An earnout period requires continued attention to how the practice operates.
Scheduling, patient follow-up, staffing, and billing workflows all influence performance. A seller who remains clinically active may still depend on other people to manage those processes.
That makes a shared review routine valuable.
Both sides should understand which measures are being monitored, who owns operational decisions, and how emerging problems will be addressed.
Root Data’s approach to dental software focuses on helping operators understand performance and identify what needs attention. That visibility can support discussions during a transition, provided access is appropriately authorized.
It does not replace the reporting and calculation rights established in the purchase agreement.
Understand the Measurement and Payment Timeline
The measurement period and payment date may be different.
An earnout might be assessed annually but paid only after financial statements are prepared and a review period ends.
Clarify when measurement begins, when calculations are delivered, and when payment becomes due.
The payment structure matters too.
A threshold or “cliff” arrangement may produce no payment unless the full target is met. A sliding scale may allow partial payment. Some arrangements permit later performance to offset an earlier shortfall; others assess each period separately.
Neither the headline amount nor the target alone tells you the full economic outcome.
When comparing the contingent amount with cash available at closing, consider timing, the probability of payment, and the buyer’s ability to pay.
Address Employment and Termination Conditions
Some arrangements require the seller to remain employed throughout the measurement period.
That creates questions beyond business performance.
What happens if the buyer terminates the seller without cause? What if illness prevents the seller from working? What if the location closes, the schedule is reduced, or the practice is sold again?
The agreement should explain how those events affect eligibility and payment.
Do not assume the purchase agreement and employment agreement operate independently. Their terms may interact in ways that materially affect the seller’s payout.
Have transaction counsel review those connections and a CPA assess the tax treatment. How a payment is structured and tied to employment can matter to its classification.
Require a Practical Way to Review the Calculation
A seller needs enough information to understand whether the earnout was calculated correctly.
The relevant records depend on the formula. They may include production and collection reports, financial statements, expense detail, provider activity, adjustments, or aggregated patient retention measures.
Reporting rights should specify the information provided, the timing, and the process for raising an objection.
The agreement should also explain how disputes are resolved and whether an independent accountant or another reviewer will be involved.
A dashboard can make trends easier to monitor, but the contractual calculation may require additional accounting records or adjustments.
Access to patient-level information should remain appropriate to the seller’s authorized role and the purpose of the review.
What Changes When the Buyer Is a DSO?
A DSO may introduce group-level systems, centralized billing, shared staffing, or management charges after acquisition.
Those changes may improve operations, but the earnout formula must account for them.
If expenses are allocated to the practice, how are they calculated? If patients or providers move between locations, how is the associated activity attributed? If reporting systems change, how will the parties maintain comparable measurements?
DSO analytics can help operators review location-level performance within a larger organization.
For the seller, the important distinction is between the group’s management reporting and the specific calculation governing the earnout. The agreement should make clear which controls payment.
Compare Full, Partial, and Zero-Payment Scenarios
A $3 million offer with $2 million at closing and $1 million contingent on future results is economically different from $3 million payable at closing.
Model several outcomes.
What would the transaction look like if you paid the earnout in full? What if only part were earned? What if no additional payment were received?
Review those scenarios alongside debt repayment, taxes, post-sale compensation, and personal income needs with your advisors.
This prevents the best possible outcome from becoming the only outcome considered.
It also helps clarify how much uncertainty you are prepared to accept in exchange for a higher potential price.
Build the Evidence Before Negotiating the Target
The strongest time to investigate performance is before agreeing to the formula.
Understand the trends behind collections and production. Review provider capacity and patient activity. Document unusual periods and the reasons for them.
Connected practice management software integrations can help make that operational information easier to access and review.
Combine it with the accounting records needed to assess earnings and expenses.
The objective is to enter negotiations with a clear understanding of what the practice has delivered, what may change, and which assumptions need to be tested.
Evaluate the Terms Behind the Headline Number
A well-structured earnout can give a buyer reasonable protection while allowing the seller to participate in future performance.
Its value depends on clear definitions, achievable conditions, reporting access, payment mechanics, and the allocation of control after closing.
A larger potential payment is only useful if the terms give you a credible path to receiving it.
Explore the Root Data demo dashboard to see how clearer operational visibility can help you prepare the performance questions behind an earnout discussion.
Want more insights like this?
Connect your practice management system to Root Data and get clear, actionable insights on your production, collections, and hygiene.
Explore Root Data